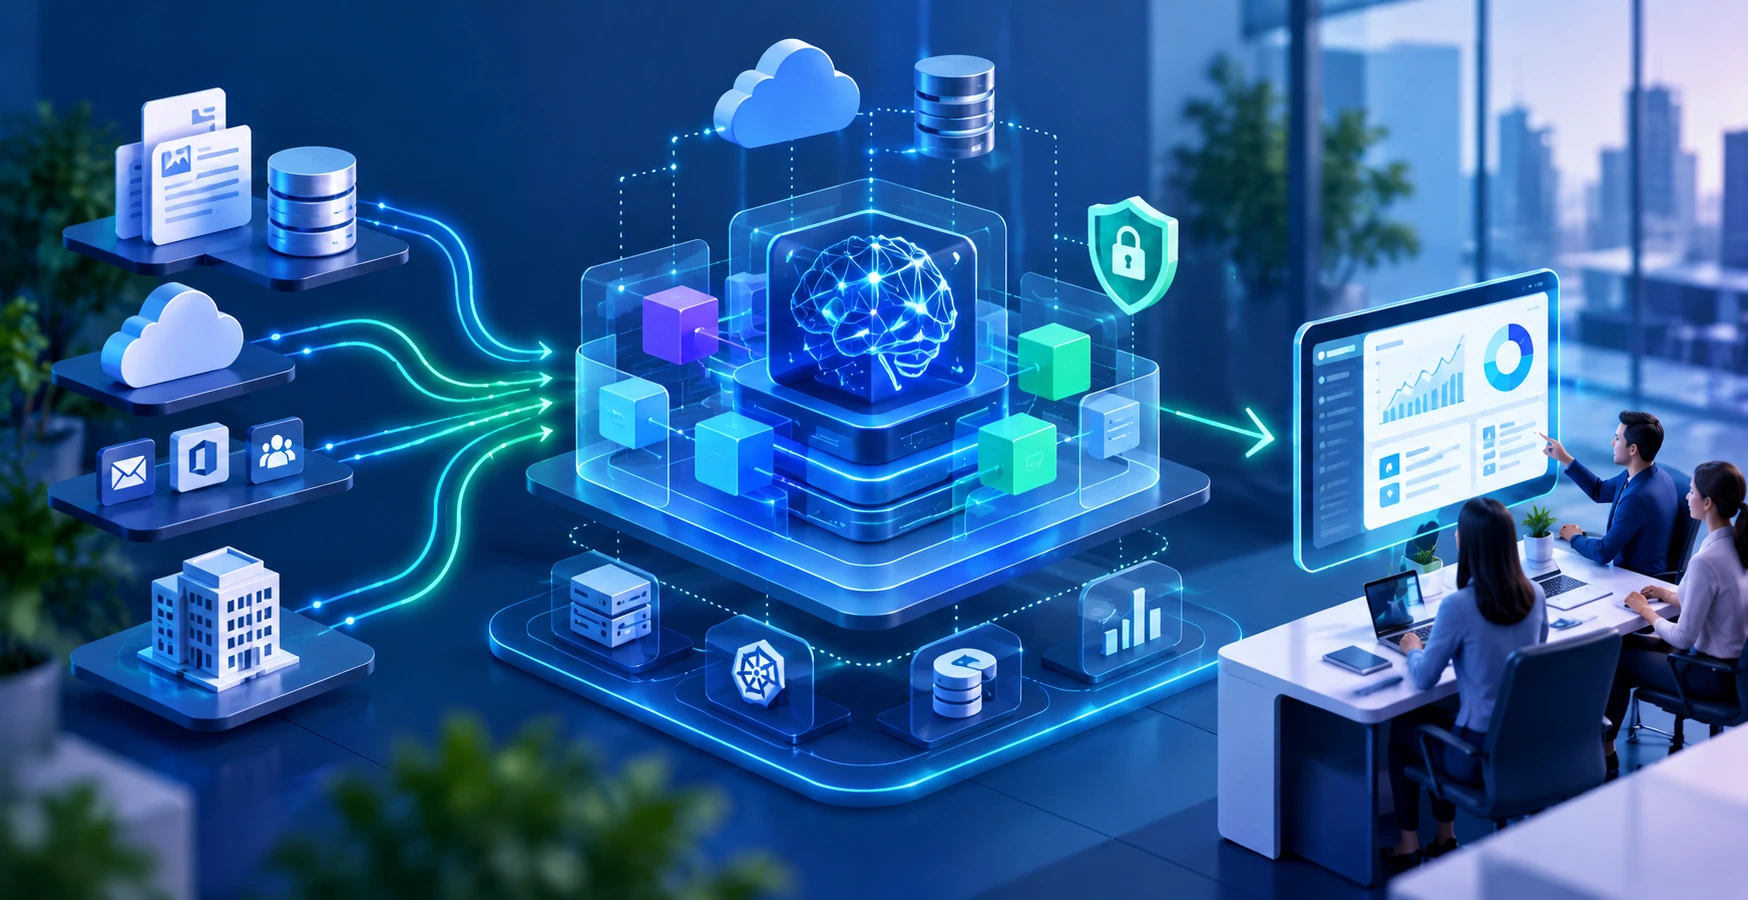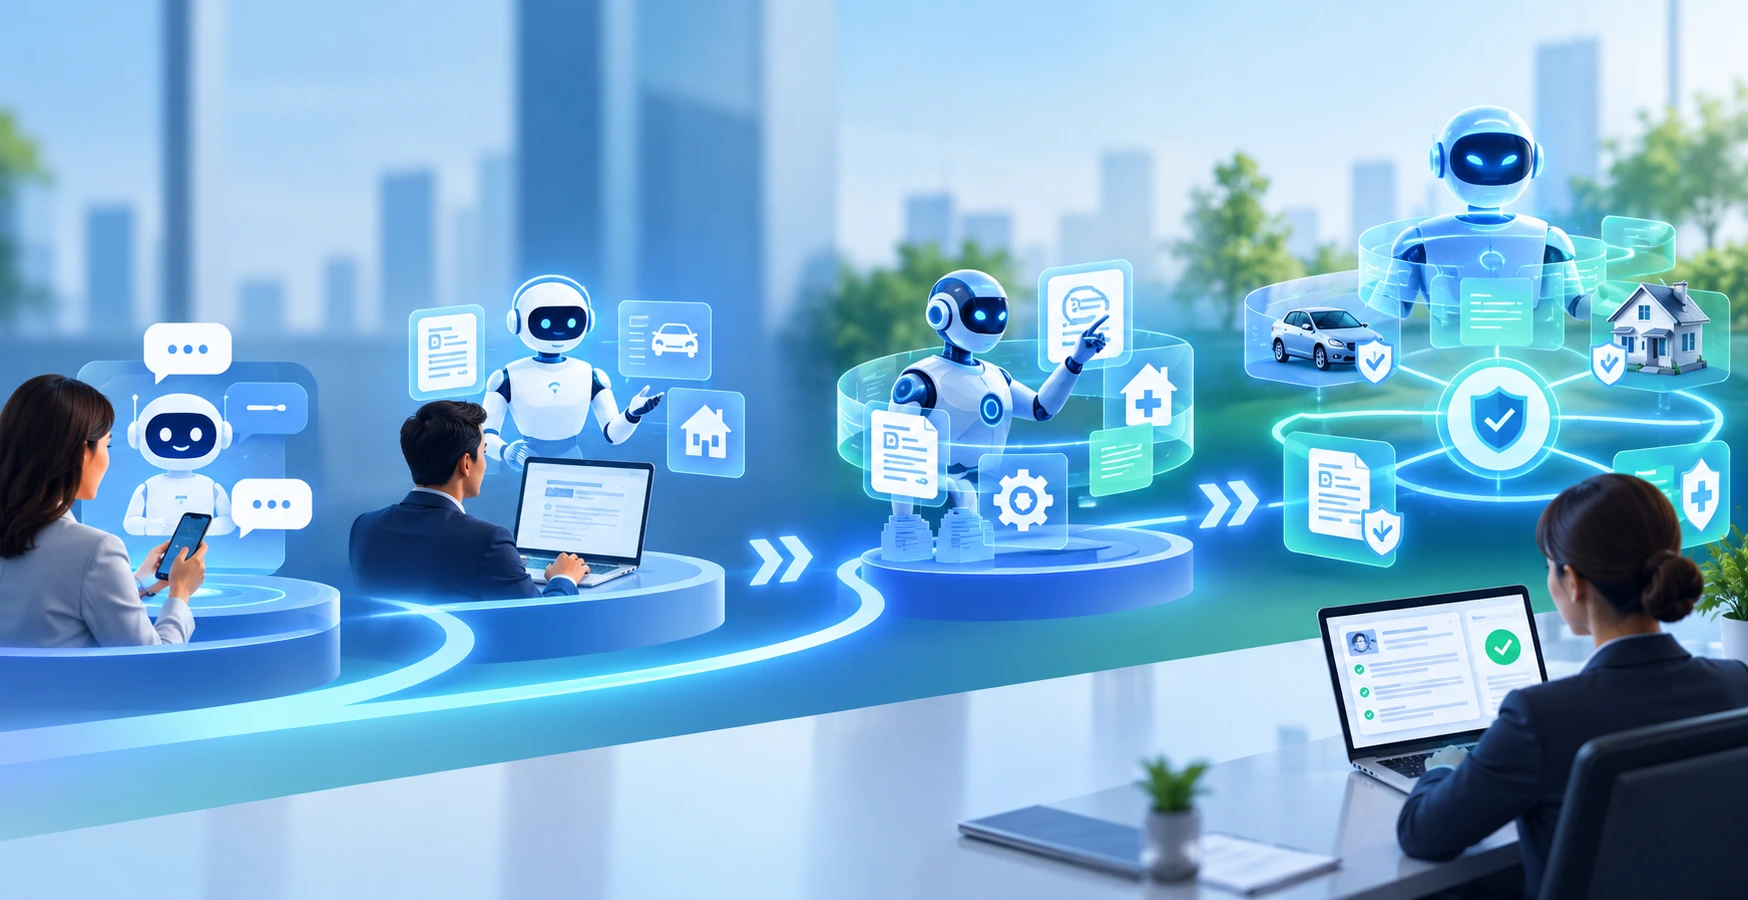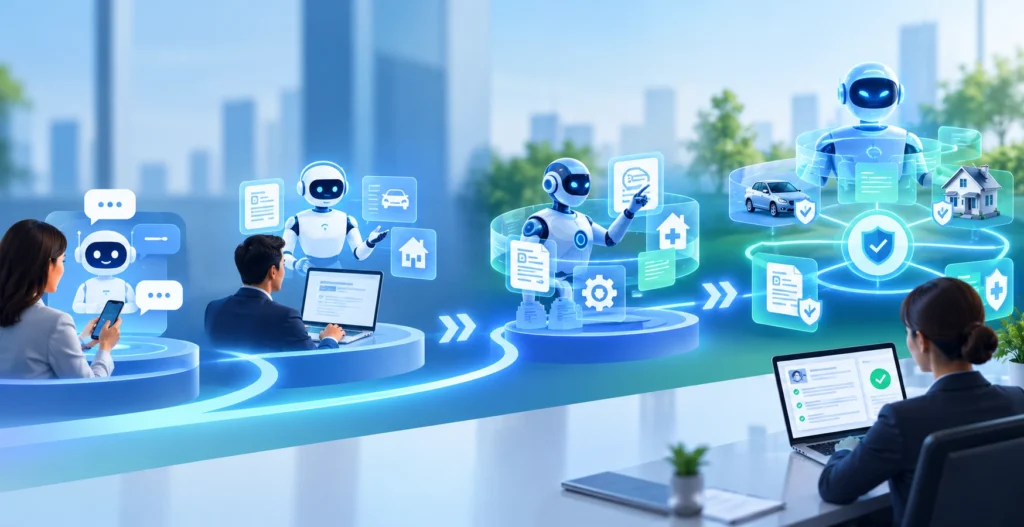
The AI maturity curve in insurance describes the progression from chatbots that answer questions to copilots that assist employees, workflow-integrated AI, agents that execute bounded tasks, and multi-agent systems that coordinate processes. Insurers should advance based on business value, data readiness, reliability, governance, and measurable outcomes—not autonomy alone.
Executive Summary
Artificial intelligence in insurance is moving beyond customer-facing chatbots toward systems that can retrieve enterprise knowledge, coordinate workflows, use approved tools, and complete bounded tasks with limited human intervention. This shift creates a new opportunity for insurers to improve customer experience, underwriting support, claims processing, fraud investigation, and back-office operations.
However, not every insurer needs autonomous AI agents. The right approach depends on process maturity, data quality, core-system integration, regulatory exposure, and the consequences of an incorrect action.
A practical AI maturity curve for insurance has five stages:
- Conversational chatbots: Answer questions and handle basic customer interactions.
- AI assistants and copilots: Help employees find information, summarize documents, and prepare recommendations.
- Workflow-integrated AI: Connect AI capabilities to business processes, systems, and defined approval steps.
- Bounded AI agents: Plan and execute approved multi-step tasks within explicit permissions and limits.
- Orchestrated multi-agent systems: Coordinate specialized agents across complex workflows under centralized governance.
The objective is not to reach the highest stage as quickly as possible. It is to move each use case to the level of autonomy that delivers measurable business value while maintaining security, explainability, compliance, and accountability.
TL;DR
- Insurance AI is evolving from answering questions to assisting employees, executing workflows, and coordinating multi-step tasks.
- Chatbots, copilots, workflow automation, and AI agents serve different purposes and should not be treated as interchangeable.
- The maturity curve is not linear: an insurer may use advanced agents in one function while retaining simpler automation in another.
- High-value use cases include claims intake, underwriting assistance, policy servicing, fraud investigation, and regulatory document processing.
- Agentic AI requires reliable enterprise data, secure tool access, explicit permissions, audit trails, and clear human escalation.
- Insurers should measure outcomes such as cycle time, accuracy, customer experience, control effectiveness, and cost per transaction—not the number of agents deployed.
- The best starting point is a bounded workflow with measurable results, followed by controlled expansion as capabilities and governance mature.
Introduction: Why the AI Maturity Curve Matters in Insurance
Insurance companies have spent years digitizing customer interactions, automating repetitive tasks, and using predictive analytics to improve risk assessment. Chatbots and rule-based automation have helped address routine service requests, while machine learning has supported fraud detection, pricing, underwriting, and claims analysis.
Generative AI has expanded these capabilities by allowing employees and customers to interact with information through natural language. AI assistants can summarize policy documents, search internal knowledge, draft communications, and help professionals interpret complex information.
The next shift is toward AI agents that can do more than generate a response. Depending on their design, agents can break a goal into steps, retrieve information, call approved tools, update records, and coordinate tasks across systems. This creates opportunities to automate more of the insurance value chain—but also introduces new operational and governance challenges.
The European Insurance and Occupational Pensions Authority (EIOPA) reported in February 2026 that nearly two-thirds of surveyed European insurance undertakings were actively using generative AI. Its findings also showed that many use cases remained at proof-of-concept stage, with insurers taking a cautious approach to adoption and human oversight. EIOPA’s generative AI market survey provides useful context for understanding the gap between experimentation and operational maturity.
For insurance leaders, the key question is no longer simply whether to use AI. It is which level of AI capability fits each business process, what must be in place before moving forward, and how should success be measured?
What Is the AI Maturity Curve in Insurance?
The AI maturity curve in insurance is a framework for understanding how AI capabilities evolve from answering questions to supporting decisions, executing business tasks, and coordinating workflows across enterprise systems. It helps insurers assess their current capabilities, identify the next practical step, and establish the technical and governance requirements needed for responsible adoption.
The five-stage model in this article is a decision framework, not a formal regulatory classification or a universal industry standard.
The five stages of AI maturity
| Stage | AI capability | Typical insurance application | Human role |
|---|---|---|---|
| 1. Chatbots | Answer questions and handle simple interactions | Policy FAQs and basic service requests | Handles exceptions and complex requests |
| 2. Assistants and copilots | Retrieve knowledge, summarize, draft, and recommend | Underwriting research and claims summaries | Reviews and makes decisions |
| 3. Workflow-integrated AI | Connect AI outputs to defined business processes | Document intake and claims triage | Approves defined steps and exceptions |
| 4. Bounded AI agents | Execute approved multi-step tasks using tools | Gather claim documents and update case status | Sets boundaries and approves higher-risk actions |
| 5. Multi-agent orchestration | Coordinate specialized agents across workflows | Claims coordination across intake, validation, investigation, and servicing | Oversees outcomes, controls, and escalations |
The stages represent increasing operational capability, not an automatic progression in value. A well-designed chatbot may be more appropriate than an autonomous agent for a straightforward policy inquiry. Similarly, a deterministic workflow may be safer and more reliable than an agent for a tightly defined financial transaction.
Read our blog on RAG for Insurance: How Retrieval-Augmented AI Speeds Up Claims Processing.
Why Is Insurance Moving From Chatbots to AI Agents?
Insurance is moving from chatbots to AI agents because many insurance processes involve multiple steps, fragmented information, repetitive handoffs, and decisions that require context from several systems. Agents can potentially coordinate these activities instead of stopping after answering a question, provided the necessary integrations, permissions, and controls are in place.
1. Customer expectations are changing
Customers increasingly expect fast, convenient service across digital channels. Chatbots can answer routine questions, but they may struggle when a request requires multiple actions, such as checking claim status, identifying missing documents, initiating a follow-up, and communicating the next step.
An agent-enabled workflow may coordinate these actions within approved limits, while escalating disputed or complex cases to a human representative.
2. Insurance workflows are interconnected
A claim may involve policy verification, document collection, damage assessment, fraud screening, reserve calculations, approvals, and customer communication. An AI agent can potentially coordinate several of these activities through controlled integrations.
The benefit depends on whether systems expose reliable interfaces and whether the workflow has clearly defined decision rights.
3. Enterprise knowledge is becoming more accessible
Retrieval-augmented generation (RAG), semantic search, document intelligence, and enterprise knowledge platforms can help AI systems access approved policy wording, underwriting guidelines, claims procedures, and internal knowledge.
Better access to relevant context can improve usefulness, but retrieved information still needs source validation, access controls, and appropriate handling of conflicting or outdated documents.
4. Insurers want more than productivity gains
AI adoption is increasingly connected to operational outcomes: faster processing, lower manual effort, better employee support, improved customer communication, and more consistent control execution.
The most meaningful transformation occurs when insurers redesign processes around the capability—not when they simply add an AI interface to an inefficient workflow.
Read our blog on AI in Insurance: Benefits, Use Cases in 2026 – techment.com.
Stage 1: Insurance Chatbots—Conversational Automation
Insurance chatbots use scripted logic, natural language processing, or language models to answer questions and support routine customer interactions. They are most effective when requests are predictable, answers can be grounded in approved information, and the consequences of an incorrect response are limited.
Common chatbot use cases
- Answering frequently asked questions about policy features.
- Explaining how to submit a claim.
- Providing basic claim-status information from authorized systems.
- Helping customers locate forms and documents.
- Directing inquiries to the correct department.
- Supporting agents and brokers with basic product information.
Example: Policy servicing chatbot
A customer asks, “What documents do I need to renew my motor policy?”
The chatbot retrieves the relevant approved checklist and presents the required documents. If the question involves a disputed coverage condition or a special underwriting exception, it routes the request to a qualified employee.
Benefits
- Relatively straightforward implementation.
- Reduced volume of repetitive inquiries.
- Consistent responses to common questions.
- Availability outside standard service hours.
- A useful starting point for understanding customer interaction patterns.
Limitations
A chatbot usually operates within a narrow conversational scope. It may provide information without completing the underlying task, particularly when several systems or approvals are involved.
A poorly designed chatbot may also produce inaccurate answers, misunderstand customer intent, or expose information if identity verification and access controls are weak.
Maturity milestone: Move beyond a basic chatbot when customers or employees repeatedly need the system to complete a task rather than merely explain how to complete it.
Stage 2: AI Assistants and Copilots—Knowledge and Decision Support
AI assistants and copilots help insurance professionals work with complex information by searching approved knowledge sources, summarizing records, drafting communications, and preparing recommendations. They improve access to information and reduce manual preparation, while keeping employees responsible for material decisions.
Common insurance use cases
Underwriting assistance
An assistant can summarize a submission, extract relevant risk information, identify missing details, and prepare a preliminary assessment for an underwriter.
Claims summarization
An assistant can compile relevant information from claim notes, policy documents, correspondence, and supporting records into a structured summary.
Broker and agent support
A copilot can retrieve product information, help prepare customer communications, and identify relevant internal guidelines.
Compliance support
An assistant can search regulatory guidance, summarize internal procedures, and help assemble documentation for review.
Employee knowledge management
A governed enterprise search assistant can help employees find information across approved documents without manually searching multiple repositories.
Example: Underwriting copilot
An underwriter receives a commercial insurance submission containing application forms, loss history, property information, and supporting documents.
The copilot extracts key facts, identifies missing information, summarizes relevant underwriting guidelines, and produces a draft assessment with links to the source material. The underwriter validates the information and makes the final decision.
What insurers need at this stage
- Governed access to enterprise documents.
- Reliable retrieval and source citations.
- Data-quality and document-version controls.
- Evaluation of factual accuracy and completeness.
- Privacy and security safeguards.
- Clear separation between AI recommendations and authorized decisions.
Maturity milestone: Progress when the organization needs repeatable task execution, system updates, or coordinated actions—not just improved employee productivity.
Stage 3: Workflow-Integrated AI—From Assistance to Execution
Workflow-integrated AI embeds intelligence into defined business processes, connecting models to business rules, systems, queues, approvals, and exception handling. It can trigger the next approved step when conditions are met, while preserving deterministic controls for critical operations.
This stage often provides a practical bridge between standalone assistants and more autonomous agents.
Insurance workflow examples
- Extracting information from claim forms and populating approved fields.
- Classifying incoming documents and routing them to the correct team.
- Checking whether required underwriting documents are present.
- Flagging claims that need additional review.
- Generating draft communications when a case reaches a defined status.
- Routing policy changes for approval according to business rules.
Example: AI-assisted claims intake
A customer submits a claim with a description, photographs, and supporting documents.
The workflow:
- Extracts relevant information from the submission.
- Checks whether required fields and documents are present.
- Retrieves authorized policy information.
- Classifies the claim and identifies possible inconsistencies.
- Routes the case according to predefined rules.
- Records the result and requests missing information where appropriate.
The workflow may use AI for extraction and classification while relying on deterministic rules for mandatory fields, approval thresholds, and routing requirements.
Why this stage matters
Workflow-integrated AI can generate value without granting a system broad autonomy. It offers an opportunity to improve cycle time and reduce manual handoffs while maintaining control over how the process operates.
Maturity milestone: Consider bounded agents when processes require dynamic planning, tool selection, or handling multiple conditional steps that are difficult to maintain through fixed workflows alone.
Stage 4: Bounded AI Agents—Goal-Oriented Task Execution
An AI agent is a system that can pursue a defined goal by selecting actions, using approved tools, observing results, and adjusting its next steps within configured boundaries. In insurance, bounded agents can coordinate multi-step activities, but they should not receive unrestricted access to core systems or authority over consequential decisions by default.
Common insurance agent use cases
Claims coordination agent
Collects missing documents, checks case completeness, updates workflow status, and prepares a case summary for the claims examiner.
Underwriting preparation agent
Gathers submission information, checks required fields, retrieves applicable guidelines, and prepares a structured package for underwriter review.
Fraud investigation support agent
Collects relevant signals from approved systems, summarizes inconsistencies, and prepares an investigation brief for an authorized specialist.
Policy servicing agent
Processes approved low-risk servicing tasks, verifies required conditions, and escalates requests that exceed its permissions.
Compliance evidence agent
Retrieves evidence for a defined control, checks whether required artifacts are present, and prepares a draft evidence package for review.
Example: Claims coordination agent
A claims coordination agent receives a newly registered claim and is assigned the goal of preparing the case for examiner review.
It may:
- Verify that the claim record exists and the requesting user is authorized.
- Retrieve the approved checklist for the claim type.
- Identify missing documents.
- Send an approved request for additional information.
- Update the case status through a permitted API.
- Record the sources consulted and actions taken.
- Escalate discrepancies, suspected fraud indicators, or cases requiring specialist judgment.
The agent should stop when it reaches a policy-defined boundary. It should not independently deny coverage, make an unsupported fraud determination, or issue a payment unless that action has been explicitly authorized within a suitably validated and controlled process.
What makes an agent different from a chatbot?
A chatbot primarily responds to user requests. An agent can also plan and execute a sequence of actions toward a goal, observe tool results, and determine the next permitted step.
However, using a language model to call a single tool does not automatically make a system mature or safely autonomous. The distinction depends on the system’s actual capabilities, permissions, execution model, and controls.
Controls required for agentic insurance AI
- Distinct agent identities and accountable owners.
- Least-privilege access to data and tools.
- Explicit action permissions and transaction limits.
- Human approval for high-impact or irreversible actions.
- Runtime validation of tool calls and outputs.
- Audit logs and traceable decision records.
- Safe stopping, retry, rollback, and escalation mechanisms.
- Ongoing monitoring, testing, and incident response.
Maturity milestone: Expand to coordinated agents only when the organization can manage dependencies, shared context, delegated permissions, and end-to-end accountability.
Stage 5: Multi-Agent Orchestration—Coordinating Insurance Workflows
Multi-agent orchestration coordinates multiple specialized agents or AI-enabled services to complete a larger business process. One component may gather information, another may validate records, and another may prepare a recommendation, while an orchestration layer manages dependencies, permissions, approvals, and the overall workflow.
This stage can support complex insurance operations, but it also introduces additional failure modes and coordination overhead.
Example: End-to-end claims preparation
A controlled multi-agent workflow could include:
- Intake agent: Structures the initial claim submission.
- Document agent: Identifies and organizes supporting evidence.
- Policy information agent: Retrieves relevant policy details.
- Assessment support agent: Summarizes available evidence and identifies inconsistencies.
- Workflow agent: Routes the case and tracks missing information.
- Audit agent: Checks whether required evidence and approvals are recorded.
The agents do not need independent authority to make final claims decisions. A human examiner or an approved deterministic decision process can remain responsible for consequential outcomes.
Benefits of multi-agent orchestration
- Specialization by task or domain.
- Reuse of validated components across workflows.
- Coordination across systems and business functions.
- Better separation of responsibilities when designed correctly.
- Potential reduction in repetitive handoffs.
Challenges
- More complex debugging and incident investigation.
- Conflicting outputs between agents.
- Permission escalation or uncontrolled delegation.
- Higher monitoring and evaluation requirements.
- More dependencies on APIs, data quality, and system availability.
- Difficulty attributing a final result to individual steps unless lineage is preserved.
The orchestration layer should therefore enforce shared policy, trace each action to the responsible component, and prevent one agent from granting itself or another agent unauthorized permissions.
Maturity milestone: Treat multi-agent deployment as an operating-model change—not simply a more advanced software feature.
Chatbots vs. Copilots vs. AI Agents: What Is the Difference?
Chatbots, copilots, and AI agents differ mainly in how they contribute to a business process. Chatbots primarily answer questions, copilots support employee work, and agents can execute bounded multi-step tasks using approved tools. Workflow-integrated AI and multi-agent orchestration add further capabilities, but each requires controls appropriate to its actual level of autonomy.
| Dimension | Chatbot | Copilot or assistant | Bounded AI agent | Multi-agent system |
|---|---|---|---|---|
| Primary purpose | Answer inquiries | Assist human work | Complete a defined goal | Coordinate a larger process |
| Typical interaction | Question and response | Research, summarize, recommend | Plan and execute steps | Delegate and coordinate tasks |
| System access | Often limited | Read access or selected tools | Explicitly authorized tools | Controlled access across components |
| Decision authority | Usually low | Human retains decisions | Bounded by policy | Depends on orchestration and approvals |
| Error handling | Clarification or escalation | Human verifies output | Stop, retry, or escalate | Cross-agent validation and escalation |
| Audit requirements | Conversation and source records | Output, sources, reviewer actions | Tool calls, state changes, approvals | End-to-end lineage and agent-level logs |
| Suitable use cases | FAQs and basic servicing | Underwriting research and claims summaries | Document collection and case preparation | Coordinated claims or servicing workflows |
The correct choice depends on the workflow, not on which technology sounds most advanced. For stable, highly structured tasks, conventional automation may remain the better option.
How Mature Is AI Adoption in the Insurance Industry?
Insurance AI adoption is expanding, but maturity varies substantially by company, function, and use case. EIOPA’s February 2026 survey of 347 insurance undertakings across 25 countries found that nearly two-thirds were actively using generative AI, while most reported use cases were still at proof-of-concept stage. The evidence points to growing experimentation alongside cautious operational deployment.
EIOPA also reported that 64% of surveyed generative AI use cases targeted back-office productivity, while 36% involved customer-facing applications. Its report described agentic AI use cases at different development stages, including customer-facing and back-office activities. These figures refer to reported use cases in the survey; they should not be interpreted as the percentage of all insurers operating mature autonomous agents.
Source: EIOPA — Generative AI Market Survey: Outlook, Use Cases and Risk Management
Several factors help explain the gap between experimentation and production:
- Legacy core systems and fragmented data.
- Difficulty integrating AI with existing workflows.
- Concerns about privacy, security, and regulatory compliance.
- Limited internal skills in AI engineering and governance.
- Uncertainty about how to measure business value.
- Challenges in validating reliability across edge cases.
- Need for clear accountability when systems take actions.
Insurers should interpret maturity as a combination of technical capability, process readiness, governance, and demonstrated outcomes—not simply the number of AI pilots or tools in use.
How Should Insurers Assess Their AI Maturity?
Insurers can assess AI maturity by evaluating five dimensions: business-process readiness, data and integration, AI reliability, governance and control, and measurable business outcomes. A maturity assessment should identify the current capability for each use case and define the evidence required before moving to a higher level of autonomy.
A practical AI maturity scorecard
Rate each dimension from 1 to 5.
| Dimension | Level 1: Initial | Level 3: Established | Level 5: Advanced |
|---|---|---|---|
| Process readiness | Informal and inconsistent | Defined workflow and ownership | Continuously optimized process |
| Data and integration | Fragmented data and manual access | Governed sources and stable integrations | Reliable cross-system context and lineage |
| AI reliability | Limited evaluation | Documented testing and performance thresholds | Continuous evaluation and controlled change |
| Governance | Ad hoc approvals | Defined permissions and oversight | Risk-tiered controls with ongoing monitoring |
| Business outcomes | Anecdotal benefits | Baselines and tracked KPIs | Sustained, independently reviewed results |
The scorecard is an internal planning aid, not a certification or regulatory rating. Scores should be supported by evidence such as test results, control records, data-quality metrics, approval workflows, and measured outcomes.
Readiness questions before moving to agents
- Is the underlying process stable and documented?
- Are the relevant data sources accurate, authorized, and accessible?
- Can the system verify the results of its actions?
- Are tool permissions narrow and explicit?
- Can the workflow stop safely when uncertain?
- Are material decisions reviewed by an accountable person?
- Can the insurer reconstruct what the system did and why?
- Are operational benefits measured against a baseline?
If several answers are no, the next step may be to improve the workflow, data, and controls rather than increase autonomy.
Read our blog on Microsoft Fabric for Insurance Carriers: A Reference Architecture
Best Insurance Use Cases Along the AI Maturity Curve
The best insurance AI use cases are those with a clear business objective, accessible data, measurable outcomes, and risks that can be controlled at the selected maturity level. Insurers should prioritize processes where AI can remove meaningful friction without bypassing important customer protections or regulatory controls.
| Insurance function | Early-stage AI | Advanced workflow or agentic opportunity | Critical safeguard |
|---|---|---|---|
| Customer service | FAQs and policy information | Coordinate servicing requests and follow-ups | Identity verification and escalation |
| Claims | Document summaries and status answers | Collect evidence and prepare cases for review | Human review of consequential decisions |
| Underwriting | Submission summarization | Gather missing information and prepare risk files | Underwriting authority and fairness controls |
| Fraud investigation | Flag suspicious patterns | Assemble evidence and route cases for investigation | Do not treat risk signals as proof |
| Policy servicing | Explain policy procedures | Execute approved changes within defined limits | Authorization and transaction controls |
| Compliance | Search policies and summarize regulations | Collect control evidence and track remediation | Source verification and auditability |
| Broker operations | Product search and drafting | Coordinate submission preparation and follow-ups | Accurate product information and permissions |
| Core modernization | Explain legacy code and documentation | Coordinate testing, mapping, and reconciliation tasks | Independent testing and change approval |
A practical prioritization framework
Score each proposed use case against five factors:
- Business impact: How much time, cost, quality, or customer friction could be improved?
- Feasibility: Are data, APIs, process definitions, and system access available?
- Risk: What would happen if the system made a wrong recommendation or took an incorrect action?
- Verifiability: Can results be checked against trusted records or deterministic rules?
- Repeatability: Does the process occur often enough to justify implementation and monitoring costs?
Start with high-impact, feasible, and verifiable use cases. A high-impact but high-risk use case may still be appropriate, but it typically needs stronger controls, narrower scope, and more extensive validation.
What Technology Foundations Do Insurers Need for Agentic AI?
Insurers need governed data, secure integration, reliable orchestration, model evaluation, identity management, and observability to deploy AI agents safely. Agents cannot compensate for missing business rules, poor source data, unreliable APIs, or unclear decision authority; these foundations must be addressed before autonomy expands.
1. Enterprise data and knowledge foundations
Insurers should establish trusted access to policy wording, claims records, underwriting guidelines, procedures, and other approved sources. Data engineering, metadata, access control, and lineage help ensure that AI systems use the right information in the right context.
2. Retrieval-augmented generation
RAG connects language models to approved information sources and can provide citations or source references. It is particularly useful for internal knowledge retrieval and document-heavy processes, but it does not guarantee correctness. Insurers should evaluate retrieval quality, permissions, stale documents, conflicting sources, and answer accuracy.
3. API and workflow integration
Agents need controlled interfaces to retrieve information or perform actions. APIs should enforce authorization, validate inputs, restrict operations, and return reliable status information. High-impact operations should not rely solely on the model’s own judgment.
4. Agent orchestration
An orchestration layer manages task execution, dependencies, retries, state, permissions, and escalation. It should support deterministic checkpoints and make it possible to stop or resume workflows safely.
5. Identity and access management
Each agent and service should operate with an identifiable owner and narrowly scoped permissions. Credential handling, delegation, revocation, and access review become especially important as agents interact with more systems.
6. Observability and evaluation
Insurers should track output quality, tool calls, latency, failures, cost, exceptions, and business outcomes. Evaluation should cover both normal scenarios and challenging cases such as conflicting records, missing information, unauthorized requests, and service outages.
Governance and Risk Management Across the Maturity Curve
AI governance must grow alongside an insurer’s level of automation. A chatbot that provides general policy information and an agent that updates claim records or initiates payments do not have the same risk profile. Controls should reflect the potential impact, the permissions granted, and the consequences of failure.
Governance controls by stage
| Stage | Governance priorities |
|---|---|
| Chatbots | Approved knowledge, privacy, safe responses, customer escalation |
| Copilots | Source validation, data access, output review, employee accountability |
| Workflow-integrated AI | Process controls, approval gates, exception handling, change management |
| Bounded agents | Agent identity, least privilege, runtime checks, action limits, audit logs |
| Multi-agent systems | Delegation controls, end-to-end lineage, shared policy enforcement, incident containment |
Insurers should also maintain an inventory of AI use cases, document intended purposes and limitations, assess third-party dependencies, and define procedures for testing, monitoring, incident response, and retirement.
In the United States, the National Association of Insurance Commissioners (NAIC) provides information on insurance AI governance and its Model Bulletin on the Use of Artificial Intelligence Systems by Insurers. Applicability depends on the relevant jurisdiction and regulatory requirements. The NIST AI Risk Management Framework can provide a broader structure for identifying, measuring, managing, and governing AI risks.
References:
A Practical Roadmap: From Chatbots to Agents
Insurers should move from chatbots to agents through a staged roadmap that starts with business outcomes, establishes reliable foundations, validates bounded use cases, and expands only when performance and governance evidence justify it. This avoids investing in autonomy before processes, data, integrations, and controls are ready.
Phase 1: Establish the baseline
Inventory current chatbots, copilots, machine learning systems, and workflow automation. Identify business owners, operating costs, pain points, data dependencies, and existing controls.
Deliverable: AI use-case inventory and baseline metrics.
Phase 2: Prioritize use cases
Evaluate candidate processes for impact, feasibility, risk, verifiability, and repeatability. Select a bounded workflow with a clear success criterion.
Deliverable: Prioritized roadmap and pilot charter.
Phase 3: Strengthen data and integration
Connect the pilot to approved sources and systems. Validate data quality, API behavior, access permissions, and exception handling.
Deliverable: Governed data and integration design.
Phase 4: Build and evaluate
Test accuracy, task completion, tool-call correctness, failure handling, security, and cost. Include edge cases and adversarial scenarios relevant to the workflow.
Deliverable: Evaluation results, documented limitations, and approval criteria.
Phase 5: Pilot with human oversight
Run the AI-assisted process under defined operating limits. Compare results against the existing process and record errors, overrides, escalations, and user feedback.
Deliverable: Pilot performance report and remediation plan.
Phase 6: Operationalize and scale
Deploy monitoring, ownership, incident response, change management, and periodic access and performance reviews. Expand to additional tasks only when evidence supports the next level of capability.
Deliverable: Production operating model and controlled scaling plan.
How Should Insurers Measure AI Maturity and Business Value?
Insurers should measure AI maturity by combining operational performance, task reliability, customer outcomes, risk-control effectiveness, and the ability to manage AI systems in production. The number of agents deployed is not a meaningful success metric on its own.
| KPI | What it measures | Why it matters |
|---|---|---|
| End-to-end cycle time | Time required to complete a process | Measures operational speed |
| Straight-through processing rate | Share of eligible cases completed without manual intervention | Tracks automation within approved boundaries |
| First-pass accuracy | Share of outputs correct without rework | Indicates reliability |
| Human override rate | Frequency of reviewer corrections or rejections | Reveals quality and control gaps |
| Exception rate | Share of cases requiring escalation | Helps identify process limitations |
| Customer satisfaction | Customer feedback on the service experience | Measures customer impact |
| Cost per transaction | Total operating cost per completed case | Supports ROI assessment |
| Audit-log completeness | Share of relevant actions with required records | Measures traceability |
| Policy violation rate | Frequency of unauthorized or out-of-policy actions | Tracks operational risk |
| Recovery time | Time to restore a workflow after failure | Measures resilience |
Establish a baseline before deployment and segment metrics by use case, product, channel, and risk category where appropriate. Include the costs of integration, evaluation, oversight, licensing, monitoring, and incident management in ROI calculations.
Common Mistakes Insurers Should Avoid
Insurers can undermine AI maturity by moving to more autonomous systems before establishing reliable processes, trusted data, measurable outcomes, and effective controls. Avoiding premature autonomy is often more valuable than selecting a more advanced model.
- Treating every chatbot as a stepping stone to agents: Some tasks are best handled by simple, predictable systems.
- Automating broken processes: Standardize the workflow and clarify decision rights before introducing AI.
- Granting broad permissions: Limit each agent to the tools and actions it needs.
- Ignoring legacy integration: Assess system reliability, API availability, and data consistency early.
- Confusing generated explanations with verified evidence: Preserve source records and validate material outputs.
- Scaling based on pilot enthusiasm: Require documented performance and risk evidence before expansion.
- Underestimating change management: Train employees on reviewing outputs, handling exceptions, and reporting incidents.
- Measuring activity instead of outcomes: Track operational and control improvements rather than the number of AI tools deployed.
- Overlooking agent lifecycle management: Maintain ownership, monitor changes, review permissions, and retire agents safely.
The Future of AI in Insurance: From Assistance to Governed Autonomy
The future of AI in insurance is likely to involve more deeply integrated assistants, bounded agents, and coordinated workflows operating across existing insurance platforms. The pace of adoption will depend not only on model capability, but also on data quality, integration, security, regulatory expectations, and the ability to demonstrate reliable business outcomes.
Likely developments include:
- More process-aware agents: Systems that understand task context and operate within defined business rules.
- Reusable agent components: Specialized capabilities for extraction, validation, research, communication, and reconciliation.
- Stronger identity and access controls: Dedicated agent identities, scoped permissions, and controlled delegation.
- Better evaluation and observability: Continuous testing of task completion, accuracy, cost, and policy compliance.
- AI-assisted core modernization: Agents helping document legacy systems, map business rules, generate tests, and reconcile data during migrations.
- More human-AI collaboration: Employees supervising exceptions and consequential decisions while AI handles bounded repetitive work.
- Governed multi-agent orchestration: Multiple specialized components coordinated through shared policies, traceable actions, and explicit escalation rules.
These developments do not imply that fully autonomous insurance operations are inevitable or appropriate for every process. In regulated environments, the most durable implementations are likely to be those that align autonomy with risk and preserve clear accountability.
Conclusion
The journey from chatbots to AI agents represents a shift from conversational support toward workflow execution and coordinated enterprise operations. For insurers, the opportunity extends beyond faster customer responses to more efficient claims preparation, underwriting support, policy servicing, compliance activities, and core-system modernization.
But maturity should not be measured by autonomy alone. It should be measured by whether an AI capability solves a meaningful business problem, operates reliably, integrates with enterprise systems, protects customer information, and produces evidence that its actions remain within approved boundaries.
Insurers should begin with a clear business objective, establish the data and governance foundations, validate a bounded workflow, and expand only when results justify doing so. Techment can help insurance organizations develop AI strategy, strengthen data engineering, modernize enterprise systems, and design governed AI assistants and agents aligned with business and operational requirements.
Frequently Asked Questions
1. What is the AI maturity curve in insurance?
The AI maturity curve describes how insurance AI capabilities can progress from chatbots to assistants, workflow-integrated AI, bounded agents, and coordinated multi-agent systems. It helps insurers choose the appropriate capability based on process complexity, business value, risk, and readiness.
2. What is the difference between an insurance chatbot and an AI agent?
A chatbot primarily answers questions or supports conversations. An AI agent can pursue a defined goal by selecting actions, using approved tools, and executing multiple steps within configured boundaries. Agents therefore need stronger execution controls and monitoring.
3. Why are insurers moving toward agentic AI?
Agentic AI can help coordinate multi-step insurance workflows that involve multiple systems, documents, and decisions. Potential applications include claims preparation, underwriting support, policy servicing, and back-office operations, subject to reliable integrations and appropriate governance.
4. What are the five stages of AI maturity in insurance?
A practical five-stage model includes conversational chatbots, AI assistants and copilots, workflow-integrated AI, bounded AI agents, and orchestrated multi-agent systems. This is a planning framework rather than a universal industry standard.
5. Which insurance processes are best suited to AI agents?
Potential candidates include collecting missing claim documents, preparing underwriting submissions, organizing compliance evidence, coordinating policy servicing, and routing cases. Suitable workflows have clear objectives, reliable data, verifiable results, and well-defined escalation rules.
6. How can insurers move from AI pilots to production?
Insurers should define a business objective, select a bounded use case, establish data and governance controls, test against representative scenarios, pilot with human oversight, and operationalize monitoring before scaling.
Related Reads
- AI in Insurance: Benefits, Use Cases in 2026 – techment.com
- RAG for Insurance: How Retrieval-Augmented AI Speeds Up Claims Processing
- AI-Powered Risk Assessment in Insurance: Models & Use Cases
- AI in Insurance Underwriting: From Manual Review to Intelligent Workflow Automation